PREDICTION RECORD · PUBLISHED 2026-10-03 00:05 UTC
STNG
Scorpio Tankers
EXCESS —
SECTION 01 — THE LIFECYCLE
EVERY MOVE. TIMESTAMPED.
SECTION 02 — THE RECORD SO FAR
PRICE, WITH CONTEXT.
$86.23TARGET
$96.58INVALIDATION
$79.33LAST
$86.23PUBLICATION
2026-10-03UPDATES
0
INTERACTIVE PRICE — TRADINGVIEW
THE MARKET RECORD.
SECTION 03 — WHY FINNENCE BELIEVED IT
THE CASE, ON RECORD.
Original thesis (immutable)
Record VLCC rates near $1.27M/day, used tankers pricier than new, 77.5% revenue growth, P/E 5.3, ROE 24.6%, and 95th-percentile 5-day momentum with strong RS confirm a supply-demand upcycle. Peak-cycle risk and forward P/E 15.9 cap confidence; BA tag is a mismatch.
AUDIT — INTERNAL GATES, SHOWN FOR TRANSPARENCY
STNG is a product tanker equity directly levered to record VLCC/charter rates and rising vessel asset values.
Momentum and relative strength are top-decile while valuation stays cheap; the tanker cycle is being repriced now.
20-45 days captures the current rate-driven earnings upgrade and momentum window before peak-cycle concerns dominate.
Cash yields far less than the asymmetric upside from a confirmed tanker upcycle with cheap valuation support.
Long STNG equity is the cleanest liquid expression of the tanker-rate thesis versus peers or commodity proxies.
Expected annualized +97.3% vs hurdle +9.0%.
Worth sole slot: True · Extreme supply-demand shift, top-decile momentum, cheap valuation, and no trap flags make this a rare high-conviction cyclical setup.
direct retail exposure; accessibility score 100.0.
- META — Strong 20d momentum (+19.3%, 95th pct) and broad evidence, but 5d is -3.1% (underperforming SPY by 2.9%) and confidence is only 55, so momentum is fading into the entry. Wait for a 5d stabilization/reclaim before committing; does not clearly beat STNG or SPY right now.
- GOLD — Weakest momentum in the set: 5d -3.8% (z -0.69) despite decent 20d. Thesis convergence is inverted (the linked thesis is 'gold miners under pressure as real rates rise'), so the bull case contradicts its own evidence. Fails to beat CASH or SPY.
- AEM — Oversold mean-reversion bet with 20d -11.3% (z -0.94), weakest decile RS vs sector and SPY, and the same inverted 'gold miners under pressure' thesis. No flow/price confirmation; speculative and inferior to CASH and SPY.
- CASH — ~4% yield is the hurdle; STNG clears it on expected return, so cash is the fallback only if no candidate qualifies. Keep dry powder given existing XOM/NVDA/MU/DHT exposure.
- SPY — Broad market baseline; STNG and META show superior relative strength, so SPY is not the best use of new capital here.
- STNG 5-day return +5.8% ranks 95th percentile, with 20-day relative strength +7.8% vs SPY.
- Record VLCC rates at $1.27M/day and used tankers pricier than new signal a tight, profitable cycle.
- Valuation remains cheap: trailing P/E 5.3, price-to-book 1.26, revenue growth 77.5%, ROE 24.6%.
- Attractiveness score 86.4 with momentum 1.0 and drawdown 0.96; no trap flags detected.
- STNG is a tanker stock, not Boeing; the BA subject tag is a data mismatch, not a thesis.
- Momentum rank 1.0 and 5d return +5.8% show the move is already crowded and extended.
- Forward PE 15.9 versus trailing 5.3 implies earnings are expected to fall sharply.
- Tanker rates at record $1.27M/day are peak-cycle signals, not durable earnings power.
- Close below 80 breaks medium-term uptrend
- VLCC rates fall sharply below $500k/day
- 10-day relative strength versus SPY turns negative
Theme 'industrials' members moving together (3 names, BA 20d -12.1%): GE, XLI
▸ TRADE QUALITY BREAKDOWN · COMPONENTS ×15
TRADE QUALITY BREAKDOWN
SECTION 04 · MARKET REGIME AT PUBLICATION
THE WEATHER THEN.
METHODOLOGY · PAPER ONLY
← BACK TO THE LEDGER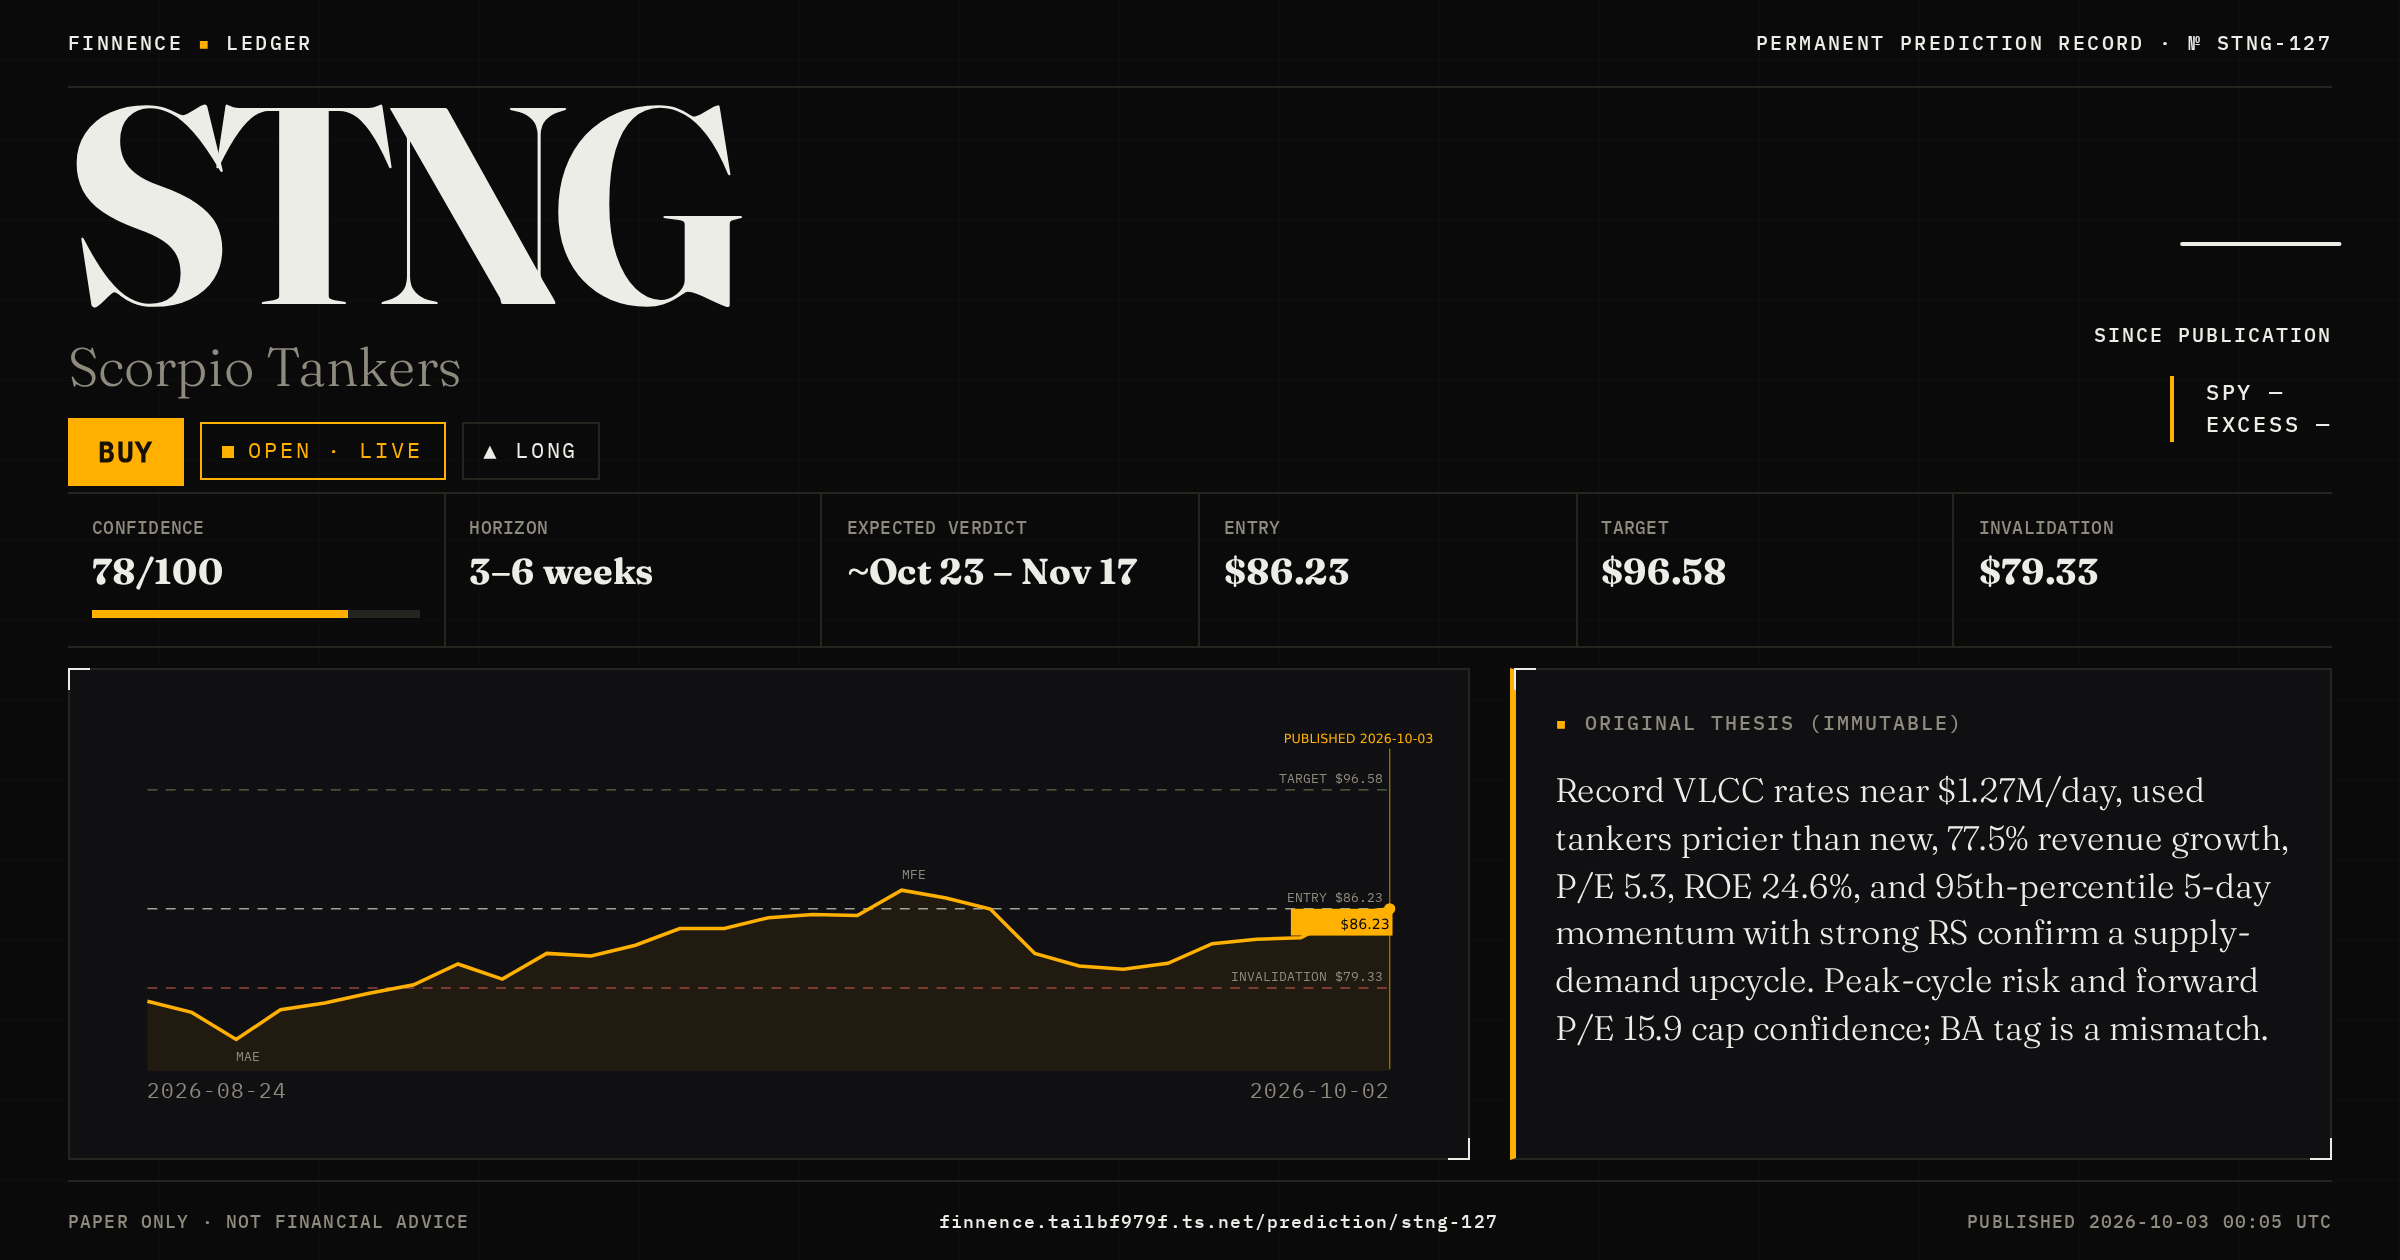
Original thesis (immutable). This permanent, timestamped record preserves the published call; later changes append and never overwrite it. PAPER ONLY · NOT FINANCIAL ADVICE.
OPEN THE MACHINE →