PREDICTION RECORD · PUBLISHED 2026-09-26 02:29 UTC
MU
Micron
EXCESS —
SECTION 01 — THE LIFECYCLE
EVERY MOVE. TIMESTAMPED.
SECTION 02 — THE RECORD SO FAR
PRICE, WITH CONTEXT.
$1,082.28TARGET
$1,212.15INVALIDATION
$995.70LAST
$1,082.28PUBLICATION
2026-09-26UPDATES
0
INTERACTIVE PRICE — TRADINGVIEW
THE MARKET RECORD.
SECTION 03 — WHY FINNENCE BELIEVED IT
THE CASE, ON RECORD.
Original thesis (immutable)
Memory-cycle leadership with 96th percentile RS, 80% operating margins, forward PE 6.8 vs trailing 24.2, and sector pricing power confirmed by memory inflation headlines. Momentum is stretched but fundamentally supported; tight supply and AI demand underpin the theme. Size modestly given 50% vol.
AUDIT — INTERNAL GATES, SHOWN FOR TRANSPARENCY
Micron Technology (MU), memory/storage semiconductor leader
Post 20d +15.7% surge with top-decile RS and strong fundamental support; volatility elevated but trend intact
14-28 days aligns with memory-storage theme window and near-term catalyst flow
Forward PE 6.8 and 13.7x earnings growth offer asymmetric upside vs cash yield
Direct equity long captures memory-cycle pricing power and AI demand
Expected annualized +156.4% vs hurdle +9.1%.
Worth sole slot: True · Top-decile momentum plus exceptional quality (80% op margin, 66% ROE) and cheap forward valuation make this a high-conviction memory-cycle leader worth the slot.
direct retail exposure; accessibility score 100.0.
- ETH-USD — ETH has strong 20d/60d momentum but 5d return is -3.0% (16th percentile), signaling deceleration. Evidence is price/event only, with no fundamental, flow, theme, or macro support, and R/R of 1.2 is the weakest of the set. Expected annualized return of 97% beats cash but the setup is less robust than MU; wait for momentum re-acceleration or a better entry.
- CASH — Cash yields 4.07% and is the risk-free baseline. It is a valid parking spot for undeployed capital, but both MU and ETH offer higher expected returns with acceptable risk controls. Cash is not the top pick because the fund is seeking growth, not preservation.
- SPY — SPY is the broad market benchmark. Neither candidate's thesis is about broad beta, and SPY offers no idiosyncratic edge. With only $627 cash available and existing XOM/NVDA exposure, adding SPY would dilute the targeted theme bet without improving risk-adjusted return.
- 20d return +15.7% with 96th percentile RS vs SPY and sector.
- Forward PE 6.77 versus trailing 24.2 signals strong expected earnings growth.
- Operating margin 80.4% and ROE 66.6% confirm exceptional quality.
- Memory inflation and SK hynix IPO news highlight sector pricing power.
- MU is up 15.7% in 20 days, 96th percentile, with 20-day volatility 50% annualized, 85th percentile.
- Relative strength vs SPY 20-day is 15.4%, 96th percentile, a stretched reading prone to mean reversion.
- Memory inflation is already hitting customers: Costco took a $152M charge on electronics, a bearish demand signal.
- SK hynix Solidigm's planned $150B IPO adds future memory supply, a competitive overhang for MU.
- Close below recent 60d drawdown level (-1.3% from high) on rising volume
- 20d relative strength vs SPY turns negative
- Memory pricing news shifts decisively bearish (e.g., contract prices roll over)
- Forward EPS estimates revised down materially
▸ TRADE QUALITY BREAKDOWN · COMPONENTS ×15
TRADE QUALITY BREAKDOWN
SECTION 04 · MARKET REGIME AT PUBLICATION
THE WEATHER THEN.
METHODOLOGY · PAPER ONLY
← BACK TO THE LEDGER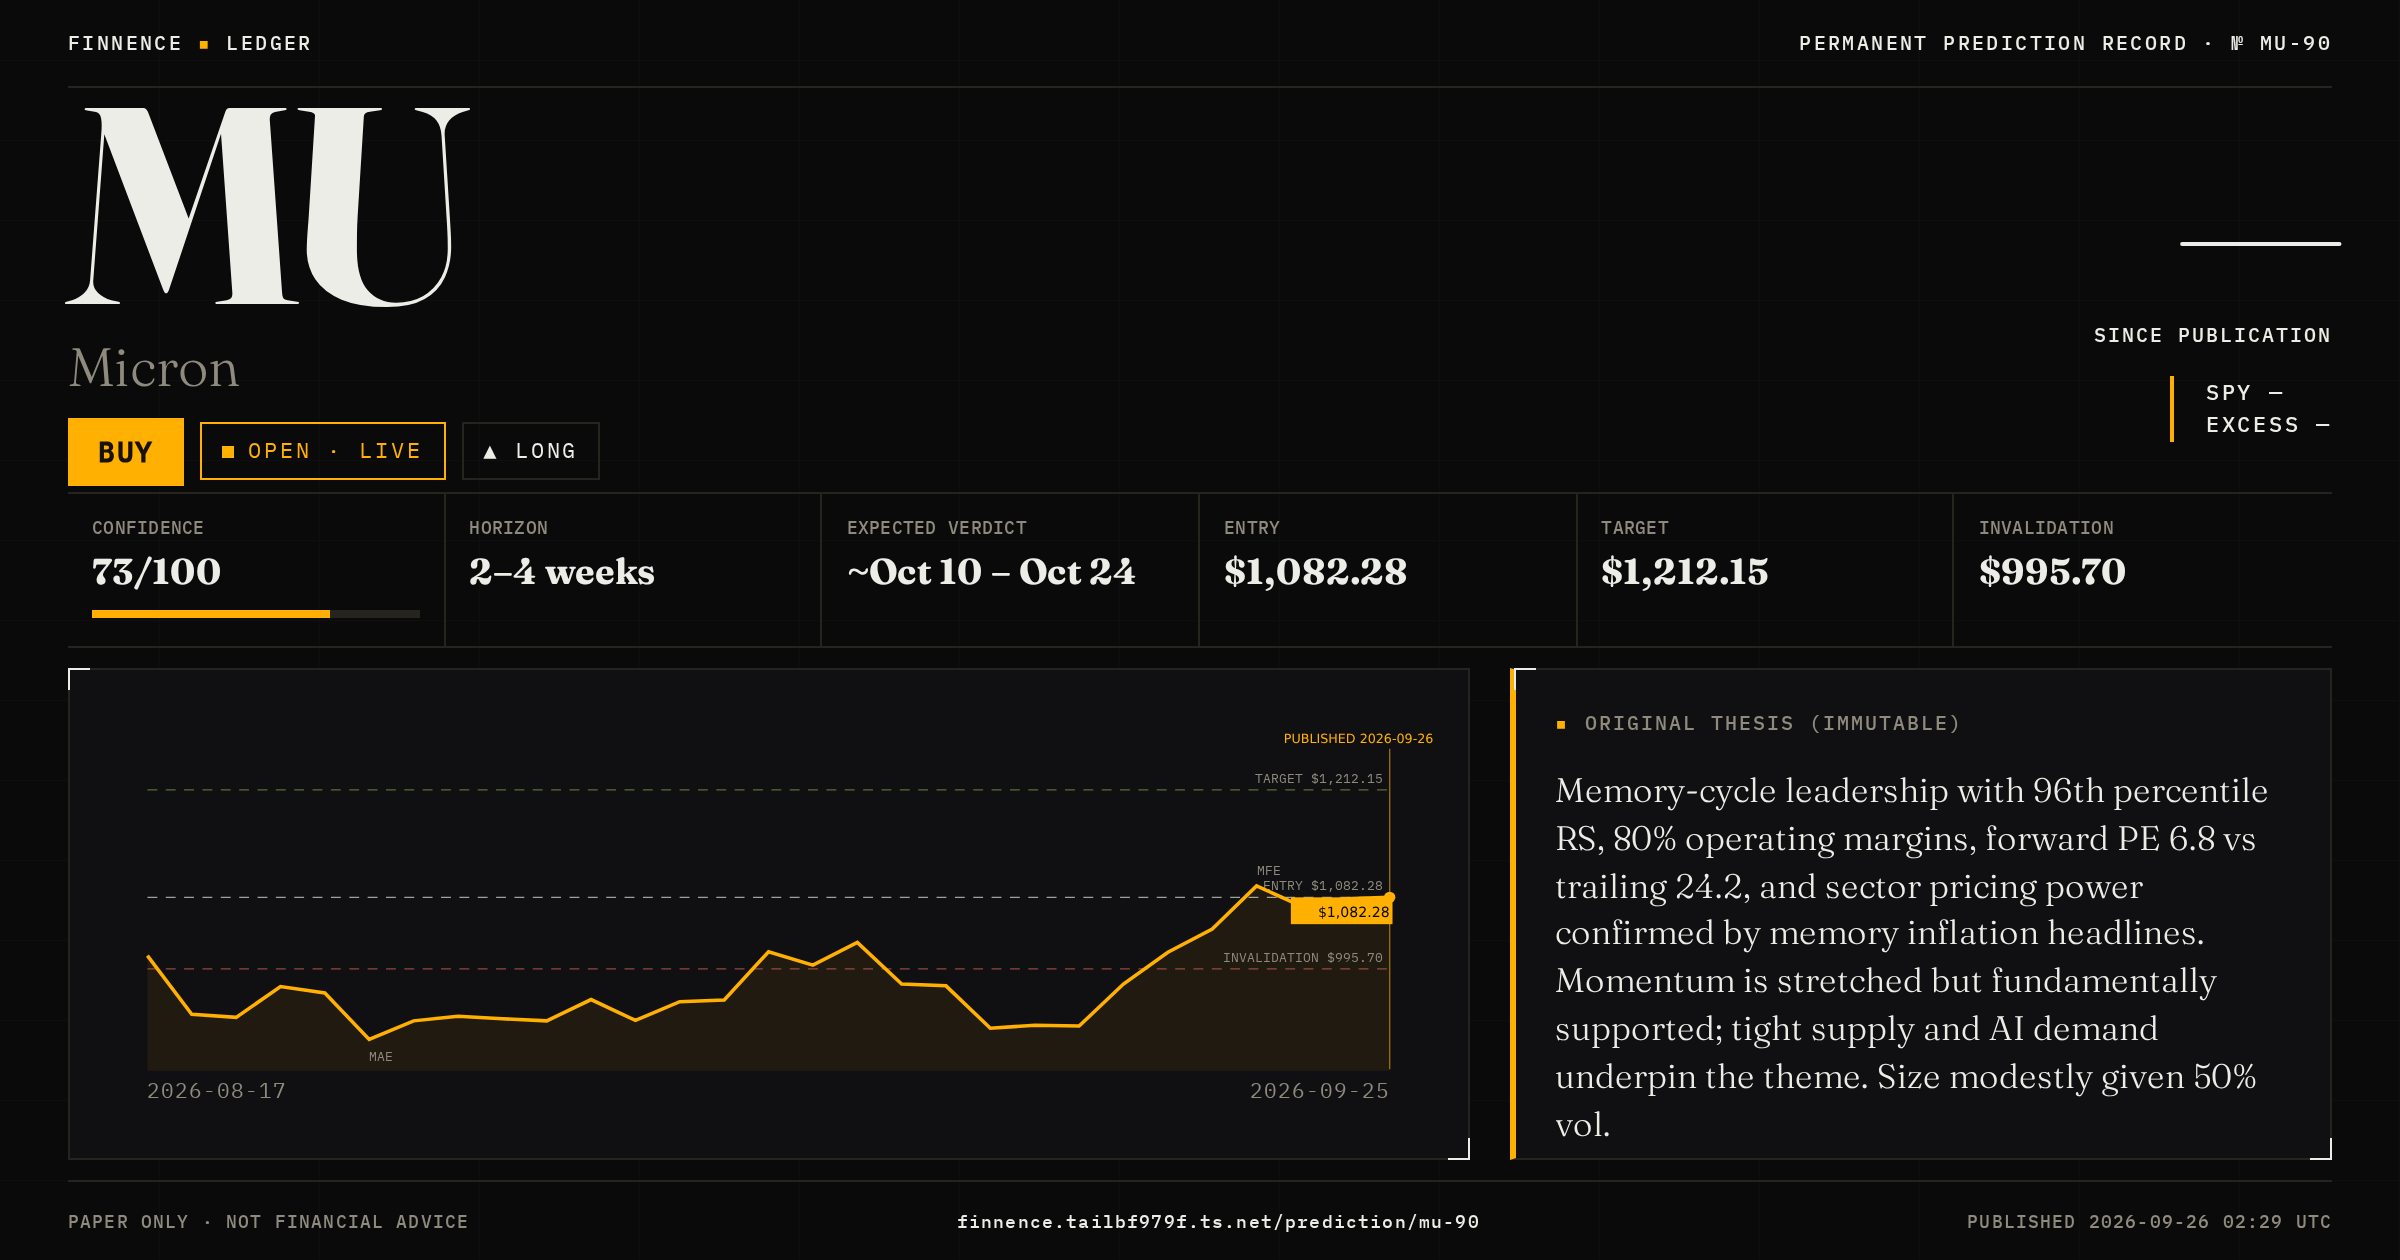
Original thesis (immutable). This permanent, timestamped record preserves the published call; later changes append and never overwrite it. PAPER ONLY · NOT FINANCIAL ADVICE.
OPEN THE MACHINE →